Tip #3: Navigate Required Minimum Distributions and SECURE 2.0
While you can leave funds in your traditional IRA to grow tax-deferred for decades, you cannot keep them there indefinitely. The federal government eventually mandates withdrawals through Required Minimum Distributions (RMDs) so it can collect traditional IRA tax on distributions. The SECURE 2.0 Act updated these rules significantly, providing retirees with greater flexibility than ever before.
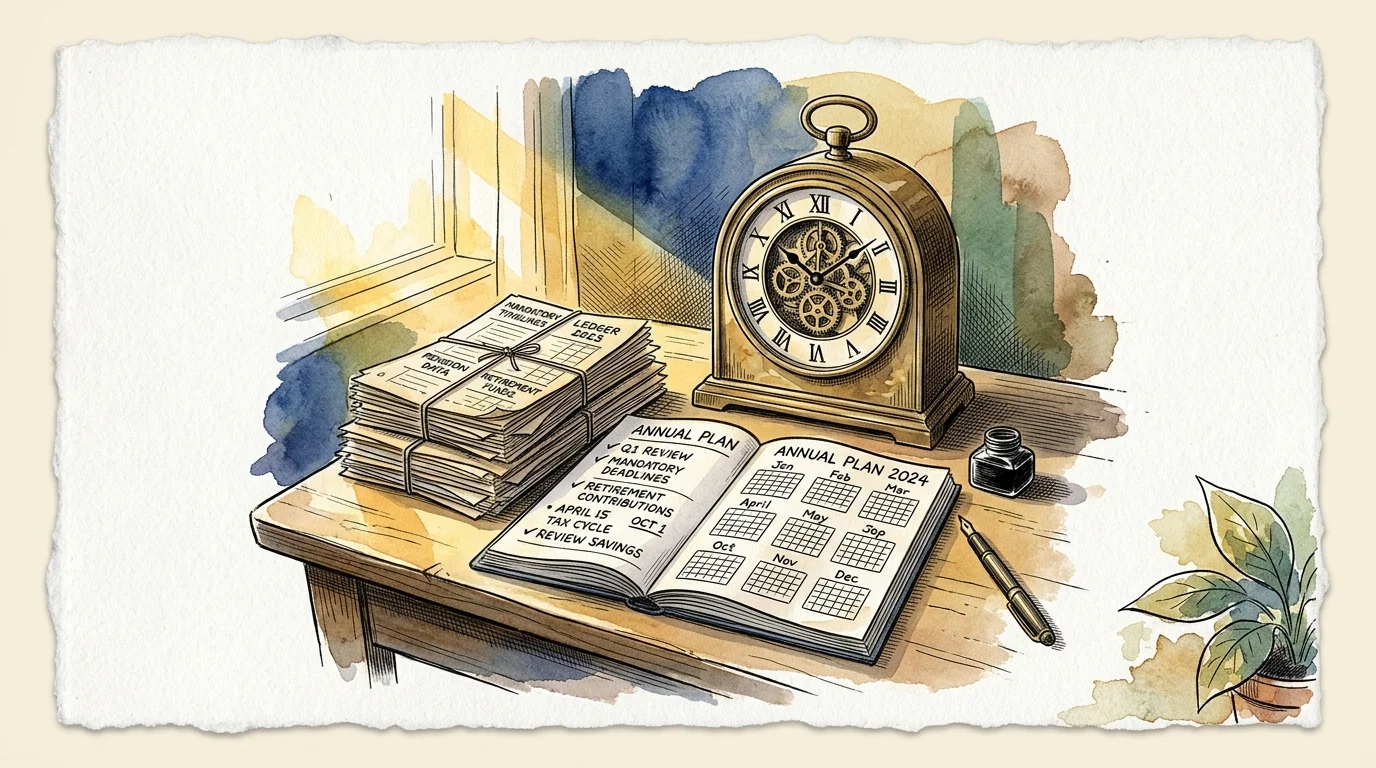
Under current law, your required starting age depends on your birth year. If you were born between 1951 and 1959, you must begin taking RMDs by age 73. If you were born in 1960 or later, your starting age shifts to 75 (taking effect in 2033). Your very first RMD must be withdrawn by April 1 of the calendar year following the year you reach your applicable RMD age. All subsequent distributions must be completed by December 31 of each calendar year.
Failing to take your full RMD on time carries a steep excise tax, though SECURE 2.0 made this penalty much more manageable. The penalty was reduced from 50% down to 25% of the shortfall amount. Furthermore, if you correct the missed distribution within a two-year correction window and submit IRS Form 5329, the penalty is reduced to 10%. Staying ahead of these deadlines ensures you keep your wealth intact and avoid unnecessary stress.