Tip #2: Claim the New Senior Tax Deduction Under the OBBBA
Tax rules surrounding your retirement checks changed dramatically following recent federal legislation. On July 4, 2025, President Trump signed the One Big Beautiful Bill Act into law as Public Law 119-21.
While campaign proposals suggested eliminating benefit taxes entirely, the final legislation created a powerful new temporary deduction. This provision delivers meaningful financial relief to millions of older Americans across the country.
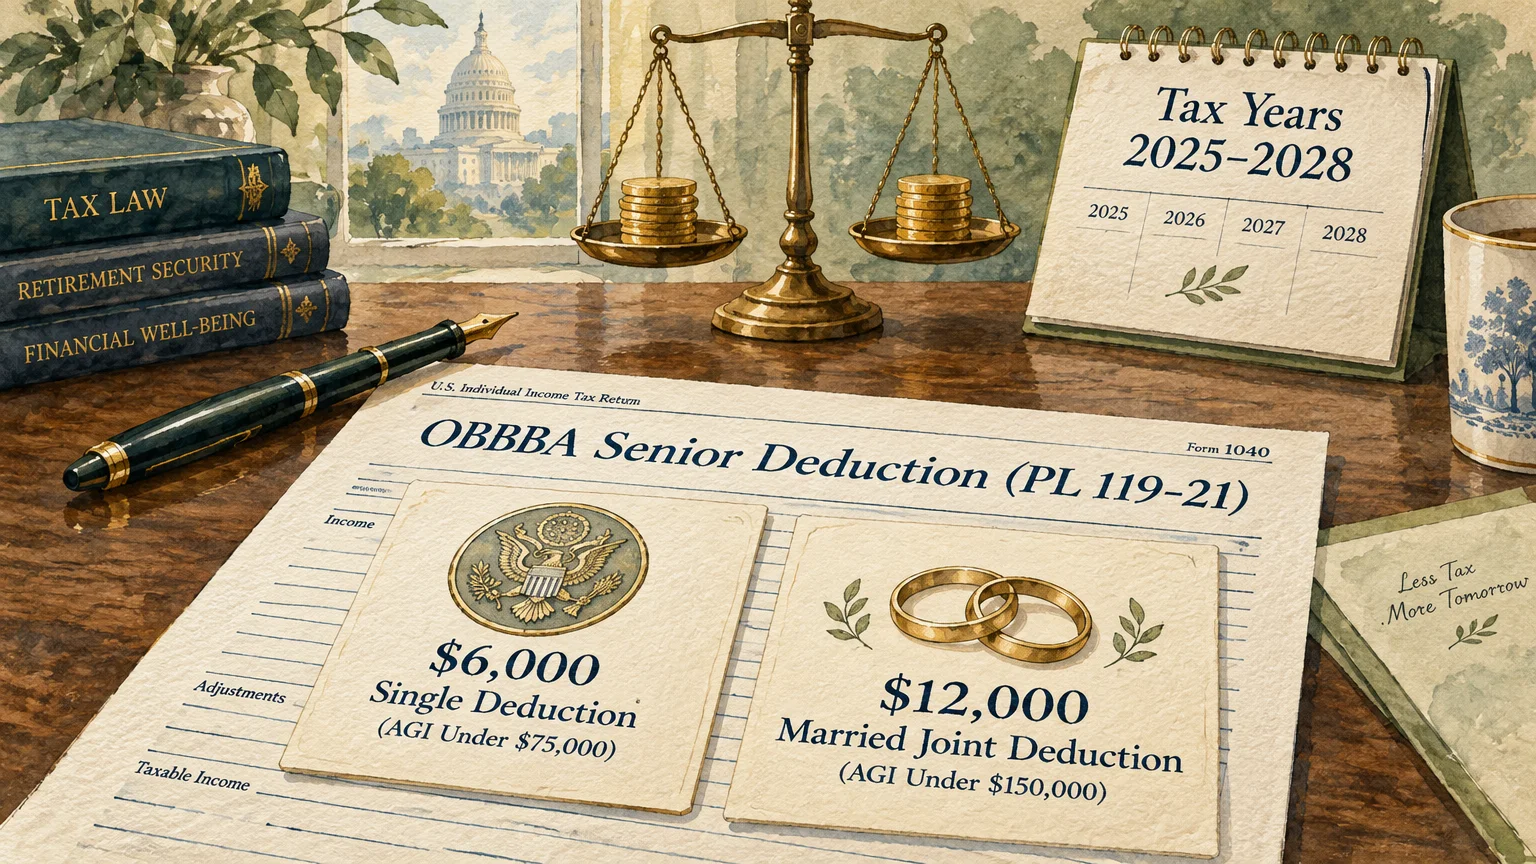
For tax years 2025 through 2028, seniors aged 65 and older can deduct up to $6,000 individually from their taxable income. This targeted deduction reduces your overall tax liability and keeps more income in your pocket.
Married couples where both spouses are 65 or older enjoy a combined deduction of up to $12,000. That substantial reduction provides immediate relief when you file your joint annual tax return.
This valuable tax deduction applies to single filers earning under $75,000 in adjusted gross income. Married couples filing jointly qualify if their combined adjusted gross income remains below $150,000.
According to the White House Council of Economic Advisers, this deduction frees roughly 88% of seniors from paying federal income tax on benefits. You can celebrate this savings by keeping more of your hard-earned money.
If your annual earnings exceed those specific income caps, standard taxation thresholds still govern your checks. Single filers with combined income between $25,000 and $34,000 face taxes on up to 50% of benefits.
Single earners reporting income over $34,000 may see up to 85% of their benefits subject to federal taxes. Joint filers face the 50% threshold between $32,000 and $44,000, and 85% above $44,000.
Carefully managing retirement account withdrawals can also help you stay under the income caps. Keeping your adjusted gross income within the statutory limits maximizes your annual $6,000 deduction.
Schedule an annual review with a certified tax professional to claim every eligible dollar under the new statute. Strategic tax filing ensures that you retain maximum wealth throughout your golden years.
Tip #3: Navigate Rising Medicare Part B Deductions and Plan Choices
Your net monthly Social Security check depends directly on automatic deductions for healthcare coverage. Most retirees pay their monthly Medicare Part B premiums straight out of their monthly retirement payment.
In 2026, the standard monthly Medicare Part B premium increased by $17.90, climbing from $185.00 to $202.90. This adjustment absorbed a noticeable portion of the 2.8% cost-of-living raise for many retirees.
Understanding this deduction helps you avoid surprises when reviewing your net bank deposits each month. Active budget management ensures that higher medical premiums never disrupt your household stability or leisure activities.
You possess significant power to offset these rising premium costs during Medicare open enrollment. This critical enrollment window runs every year from October 15 through December 7, 2026.
Use this enrollment period to compare Medicare Advantage plans and standalone Part D prescription drug options. Switching to a plan with lower copayments or lower drug deductibles can easily restore lost monthly income.
Many Medicare Advantage policies offer premium reduction credits that refund money directly back to your Social Security check. Exploring these plan options allows you to regain cash flow without sacrificing quality medical care.
Check whether your preferred doctors and prescription medications remain covered in your current network for 2027. Making timely healthcare adjustments before December 7 prevents unexpected expenses when the new year arrives.
Consult with a licensed insurance advisor or your local State Health Insurance Assistance Program for unbiased guidance. Free professional assistance helps you choose cost-effective coverage tailored precisely to your wellness needs.
Prioritizing your annual preventive healthcare checkups also lowers total medical spending over time. Maintaining robust health remains your greatest asset for living an active, joyful, and financially independent retirement.