You can build an adventurous retirement without draining your nest egg each month. A few deliberate financial adjustments will instantly unlock surplus cash for travel, creative hobbies, and memorable outings with loved ones.
Trimming your spending does not mean giving up your favorite social traditions. In fact, smart budgeting gives you the freedom to pursue new passions with complete peace of mind.
Discover five practical budget tweaks that optimize your daily cash flow. These strategic moves will help you enjoy the vibrant lifestyle you truly earned.
Lifestyle Idea #1: Optimize Healthcare and Prescription Timing
Healthcare expenses often feel unpredictable, but proactive planning puts you back in total control of your money.
When you master the timing of your medical reviews, you protect your hard-earned nest egg from unnecessary leaks.
Adopting strategic healthcare habits gives you the freedom to stretch retirement income for social adventures.
Review Your Options During Medicare Open Enrollment
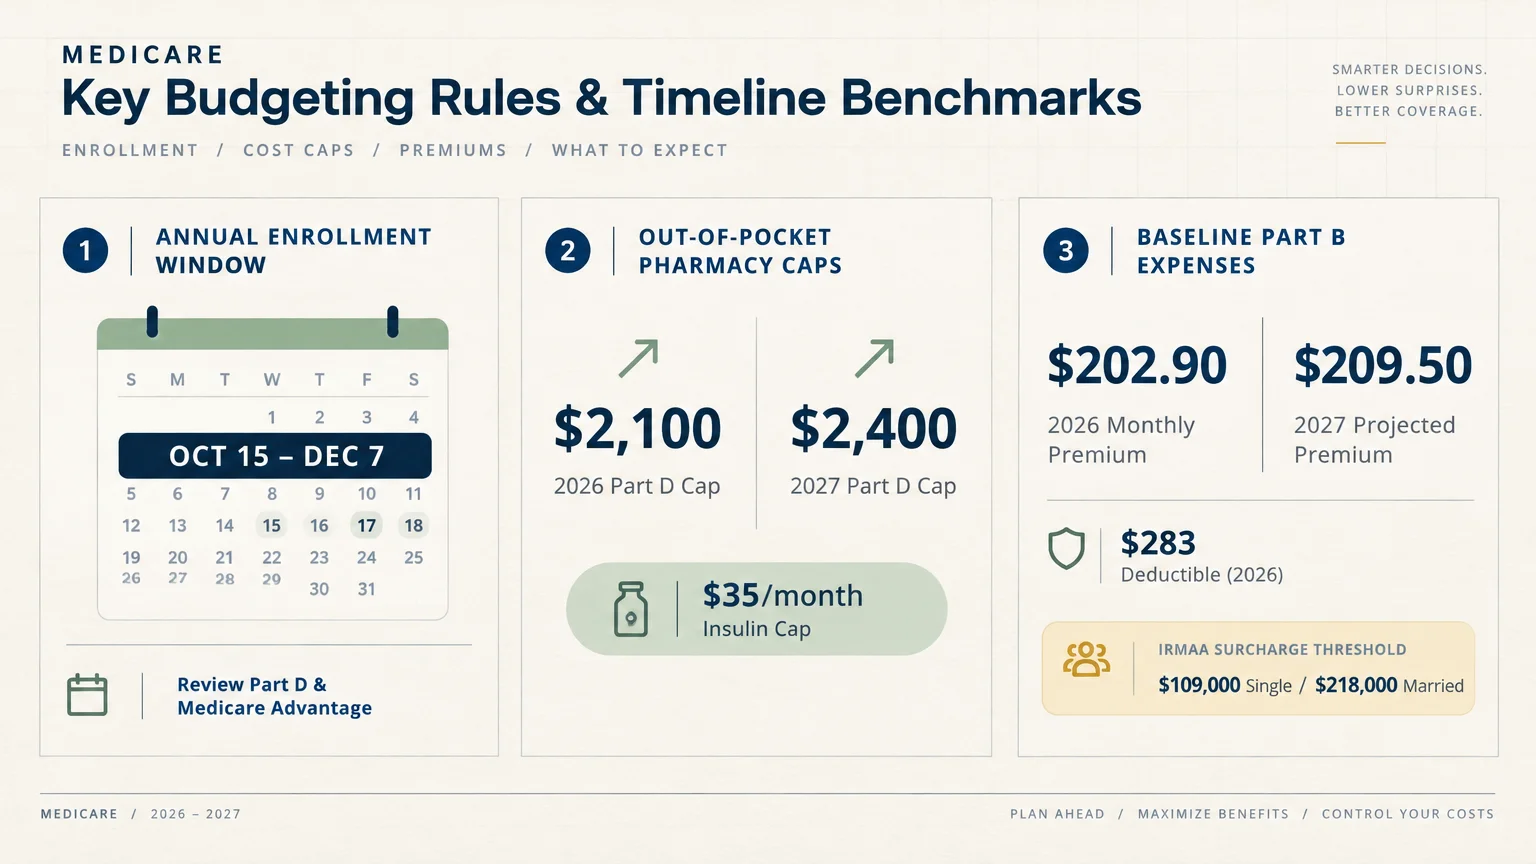
Mark October 15 through December 7 on your personal calendar every autumn.
During this annual window, Medicare beneficiaries can compare Part D drug plans and Medicare Advantage coverage for the upcoming year.
Insurers regularly alter their formularies, co-pays, and preferred pharmacy networks.
Spending an afternoon comparing plan options on official portals can reveal hundreds of dollars in annual savings.
Select a plan that covers your specific maintenance prescriptions at the lowest total out-of-pocket cost.
Taking this proactive step keeps your baseline medical expenses low and predictable.
Capitalize on Modern Prescription Caps
Recent federal updates offer unprecedented financial predictability for seniors managing ongoing prescription needs.
Under current regulations, your annual out-of-pocket spending on covered Part D prescription drugs caps at $2,100 in 2026.
This cap rises to $2,400 in 2027, preventing catastrophic pharmaceutical costs from disrupting your lifestyle budget.
You can also enroll in the Medicare Prescription Payment Plan to smooth pharmacy expenses throughout the year.
This program spreads your out-of-pocket pharmacy balances into equal monthly installments rather than demanding huge upfront sums at the counter.
Furthermore, life-saving covered insulin remains firmly capped at $35 per month with zero deductible required.
These caps make budgeting for retirees significantly more reliable throughout the calendar year.
Account for Part B Premiums and Surcharges
Predictable monthly budgeting requires tracking standard baseline expenses alongside potential surcharges.
For 2026, the standard monthly Medicare Part B premium equals $202.90, paired with an annual deductible of $283.
Trustees project that the 2027 standard Part B premium will rise by about $6.60 to reach $209.50 monthly.
Pay careful attention to Income-Related Monthly Adjustment Amount thresholds if you withdraw larger sums from retirement accounts.
In 2026, high-income surcharges begin if your 2024 modified adjusted gross income exceeded $109,000 for single filers or $218,000 for married couples.
Keep your taxable withdrawals below these levels to prevent costly automated deductions from your retirement payments.
Strategic tax planning preserves your monthly cash flow for active community pursuits.
Turn Medical Savings into Active Wellness
Reinvest the dollars you save on healthcare directly into invigorating physical and social activities.
Join a local indoor pickleball league, enroll in gentle water aerobics, or purchase premium trail walking shoes.
Group wellness activities strengthen your cardiovascular health while surrounding you with cheerful, like-minded friends.
Preventative wellness ultimately reduces your long-term medical burdens and creates room for more joy in your retirement budget.
When you stay fit, you unlock boundless energy to enjoy hobbies with your family.
Lifestyle Idea #2: Unlock Overlooked Senior Tax Deductions
Taxes remain one of the largest hidden expenses in retirement, quietly eating into your discretionary fun funds.
Claiming every deduction designed for older adults lets you redirect substantial cash back toward your personal lifestyle goals.
Smart tax filing strategies provide powerful retirement budget tips that generate instant annual liquidity.
Harness the Standard Deduction for Older Adults
Many retirees overlook the extra standard deductions granted to taxpayers aged 65 and older.
For the 2026 tax year, the base standard deduction is $16,100 for single filers and $32,200 for married couples filing jointly.
Taxpayers age 65 and older receive an additional standard deduction of $2,050 if filing single.
Qualifying married couples receive an extra $1,650 per eligible spouse, creating an immediate boost to your tax-free threshold.
These elevated standard allowances eliminate the tedious chore of itemizing receipts while significantly dropping your overall taxable income.
Ensure your tax software or preparer applies these extra allowances to capture every dollar owed to you.
Claim the Enhanced Senior Deduction
Retirees age 65 and older now possess another powerful tool under the Working Families Tax Cuts provisions.
Qualifying individuals can claim an additional Enhanced Senior Deduction of $6,000 per person between 2025 and 2028.
A qualifying married couple filing jointly can claim a combined deduction of $12,000 on their tax returns.
You can secure this generous deduction on Schedule 1-A whether you choose to itemize or take the standard deduction.
The full benefit applies until your modified adjusted gross income reaches $75,000 for single filers or $150,000 for joint filers.
Consult a certified tax specialist to position your distributions beneath these phaseout thresholds and capture maximum tax relief.
This single maneuver can shield thousands of dollars of investment returns from federal tax collectors.
Fund Memorable Social Experiences With Tax Savings
View your lower tax obligation as a direct deposit into your travel and entertainment account.
Use the extra cash to host an annual summer barbecue for your children and grandchildren.
Alternatively, fund a private pottery workshop, purchase oil paints, or subscribe to a local symphony season ticket package.
When you transform tax efficiency into shared memories, your retirement years feel genuinely luxurious without stretching your resources thin.
Deliberate tax strategies let you celebrate life while keeping your long-term nest egg secure.
Lifestyle Idea #3: Leverage Curated Travel Passes and Lifestyle Memberships
Adventures on the open road provide the excitement and social rejuvenation that define fulfilling golden years.
Strategic memberships grant you VIP access to premier destinations at a fraction of standard retail prices.
Using discounts designed for seniors allows you to save money in retirement while traveling frequently.
Explore Federal Lands With the Senior Pass
Nature lovers age 62 and older can secure the incredible America the Beautiful Senior Pass from the National Park Service.
U.S. citizens and permanent residents can purchase an annual pass for just $20 or a lifetime pass for $80.
This single card unlocks admission to more than 2,000 federal recreation sites, national monuments, and iconic national parks.
Even better, pass holders receive a 50% discount on select amenity fees, including boat launches, guided tours, and developed campsites.
Invite your friends or grandchildren along on scenic road trips, knowing that passenger vehicle entrance fees are completely covered.
Exploring pristine canyons, mountain peaks, and coastal reserves offers world-class recreation without high resort costs.
Maximize Dedicated Senior Lifestyle Memberships
Organizations designed for adults age 50 and older offer comprehensive discount networks that quickly pay for themselves.
An AARP membership costs $20 per year, which often drops to $15 annually when you select automatic renewal.
Your annual membership fee also includes a completely free secondary membership for an adult partner in your household.
Take advantage of consistent savings on car rentals, airline bookings, roadside assistance, and popular hotel chains across the country.
Members also enjoy weekly discounts on cell phone carrier bills, prescription eyeglass frames, and casual dining restaurants.
These recurring discounts compound month after month, delivering exceptional value for a tiny upfront membership investment.
Build a Thriving Community Around Group Excursions
Combine your travel discounts with friends to create memorable group getaways on a budget.
Plan weekday camping trips or cabin rentals outside peak tourist seasons to capture lower rates and avoid overwhelming crowds.
Organize a local museum tour followed by a relaxed lunch where you utilize your combined membership discounts.
Sharing travel planning duties with fellow retirees builds deep bonds and makes every adventure far more affordable and enjoyable.
Traveling with peers turns simple road trips into lifelong shared highlights.
Lifestyle Idea #4: Align Early Earnings and Social Security Timing
Many seniors discover that stepping away from traditional careers opens doors to joyful, low-stress part-time work.
Balancing flexible gig income with your benefits keeps your mind sharp and injects extra cash into your retirement spending.
Strategic scheduling lets you optimize your monthly income without encountering unexpected benefit withholdings.
Navigate Early Retirement Earnings Limits
If you claim Social Security before reaching your full retirement age, watch your annual wage thresholds carefully.
In 2026, retirees under full retirement age can earn up to $24,480 per year, or $2,040 monthly, without benefit reductions.
Earn above this cap, and the government withholds $1 in benefits for every $2 earned over the threshold.
For 2027, this early retirement earnings limit increases to $25,560 per year, which equals $2,130 each month.
If you reach full retirement age during the year, your limit jumps to $65,160 in 2026 and rises to $67,920 in 2027.
In your milestone birthday year, authorities withhold only $1 in benefits for every $3 earned above that much higher threshold.
Staying mindful of these exact thresholds protects your benefits while providing healthy supplementary earnings.
Celebrate Inflation Adjustments
Annual cost-of-living adjustments help preserve your purchasing power against rising grocery and utility prices.
Social Security benefits received a 2.8% COLA adjustment for the 2026 calendar year.
On October 14, 2026, the Social Security Administration announced a 3.6% COLA for 2027 that takes effect in January 2027.
This welcome increase raises the average retired worker’s monthly benefit by about $75, climbing from $2,095 to $2,170.
Treat these modest automatic raises as designated lifestyle funds rather than letting them disappear into vague household overhead.
Allocating this extra income toward personal enrichment keeps your spirits high and your budget balanced.
Turn Passion Projects into Guilt-Free Fun Funds
Pick up a fun, low-pressure part-time role that aligns with your personal talents and artistic interests.
Work at a botanical garden, assist at a community golf pro shop, or teach woodworking at a local maker space.
Earning $1,500 each month stays comfortably within federal limits while providing thousands of dollars in pure discretionary play money.
You can spend these earnings on spontaneous weekend getaways, theatrical performances, and special dinners without touching your investment principal.
Engaging in community-focused work keeps you socially connected and physically active throughout the week.
Lifestyle Idea #5: Reinvent Your Dining and Entertainment Routine
Social connection lies at the true heart of a happy, stimulating retirement lifestyle.
You do not need expensive restaurant checks or costly theater tickets to maintain an exciting, active social calendar.
Transforming how you gather with friends preserves your wealth while dramatically increasing your fun.
Embrace Matinees and Off-Peak Dining
Shift your dining outings toward mid-day lunches, early bird specials, and afternoon happy hours.
Upscale bistros frequently offer their signature lunch entrees at prices 30% to 50% lower than identical evening dinner plates.
Pair a delicious bistro lunch with a discounted cinema or theater matinee on a quiet Tuesday afternoon.
You will enjoy intimate conversations in quieter dining rooms while avoiding noisy weekend crowds and inflated peak pricing.
This simple shift delivers the exact same culinary excellence for half the expense.
Launch a Rotating Neighborhood Supper Club
Trade crowded restaurants for vibrant, home-cooked dinner parties hosted among your close circle of friends.
Establish a monthly rotating supper club where each couple or individual takes turns hosting a themed culinary evening.
One host prepares the main entree while guests contribute appetizers, fresh salads, crusty artisan breads, and favorite wines.
These relaxed evenings foster deeper personal conversations than noisy restaurants ever allow, all while keeping dinner costs remarkably low.
Rotate themes across international cuisines, such as rustic Italian pasta nights, Spanish tapas, or summer patio barbecues.
Cooking together creates wonderful memories and brings laughter into your home without strain on your wallet.
Tap Free Cultural Resources and Senior Audits
Your local community offers a rich tapestry of free entertainment if you know where to look.
Visit your local municipal library to check out free museum passes, state park vehicle permits, and streaming film passes.
Many state universities and community colleges allow older adults to audit undergraduate courses for free or for nominal fees.
Enroll in art history, creative writing, or conversational foreign languages alongside enthusiastic learners of all generations.
Learning new skills stimulates cognitive resilience while introducing you to inspiring instructors and passionate fellow students.
Active learning keeps your mind youthful and fills your weekdays with engaging discussions.
Audit Subscriptions and Recurring Digital Leaks
Recurring monthly charges quietly siphon away discretionary income when left unchecked for months on end.
Review your bank statements to identify streaming platforms, duplicate music apps, and unread magazine subscriptions you rarely use.
Cancel services that fail to provide genuine daily delight, or rotate single streaming platforms one month at a time.
Direct the $50 to $100 you save each month into a dedicated savings envelope for live concerts and family outings.
Eliminating automated digital waste gives you instant funding for real-world social experiences.
Putting It into Practice: Small Steps for Big Changes
Transforming your retirement budget does not require drastic sacrifices or overwhelming spreadsheets.
Taking simple, deliberate actions each week will quickly generate momentum and free up your disposable cash.
Follow these four straightforward steps to start optimizing your resources immediately.
Step 1: Set Up an Annual Financial Calendar
Begin by scheduling your crucial financial review dates across the coming twelve months.
Add Medicare Open Enrollment from October 15 to December 7 so you never miss plan comparison deadlines.
Schedule a spring tax review to confirm your eligibility for the extra senior standard deduction and Enhanced Senior Deduction.
Setting calendar reminders guarantees you capture valuable savings before important statutory windows close.
A well-organized calendar eliminates financial stress and keeps your focus on having fun.
Step 2: Create a Dedicated Fun Account
Open a separate high-yield savings account designated exclusively for leisure, hobbies, and social adventures.
Whenever a budget tweak saves you money, transfer that exact amount directly into your fun account.
Seeing this balance grow gives you full emotional permission to spend guilt-free on weekend trips and family celebrations.
Separating lifestyle funds from baseline bill money removes anxiety from your entertainment spending.
Step 3: Propose New Social Traditions
Take the lead in suggesting budget-conscious getaways and creative outings to your friend group.
Invite neighbors on a scenic hike using your America the Beautiful Senior Pass followed by an outdoor picnic.
Suggest an afternoon matinee or potluck dinner party rather than defaulting to an expensive weekend dinner reservation.
You will often discover that your friends eagerly appreciate the opportunity to save money while having great fun.
Leading with enthusiasm makes affordable gatherings the highlight of everyone’s social week.
Step 4: Audit Your Cash Flow Quarterly
Dedicate one quiet morning every three months to review your bank and credit card statements.
Ensure you are staying beneath the early retirement earnings limits if you work while collecting early Social Security benefits.
Eliminate newly creeping subscription fees and verify that your lifestyle spending matches your personal priorities.
Consistent quarterly check-ins keep your finances aligned with the rich, joyful retirement you envision.
Small adjustments prevent minor leaks from derailing your grand travel aspirations.
Frequently Asked Questions
How can I save money in retirement without feeling like I am depriving myself?
Shift your perspective from cutting expenses to reallocating your resources toward the things you love most.
When you capture tax deductions and travel discounts, you free up cash for authentic personal fulfillment.
Focus on eliminating wasteful background spending like unused subscriptions rather than sacrificing your favorite social gatherings.
What if my friends want to go to expensive restaurants that do not fit my budget?
Be proactive by suggesting alternative gathering ideas before dinner plans get locked into place.
Invite your friends to meet for an afternoon dessert and coffee, or suggest a fun weekend brunch instead.
True friends value your company and laughter far more than the price tag of the restaurant table.
What is the most effective way to prepare for unexpected healthcare spikes?
Take full advantage of Medicare out-of-pocket caps and the Medicare Prescription Payment Plan.
Setting up monthly installment options prevents sudden pharmacy bills from overwhelming your daily checking account.
Maintain an emergency medical reserve in a liquid high-yield savings account to absorb occasional copayments smoothly.
Is it worth working part-time in retirement if Social Security withholds benefits?
Working a part-time job remains highly rewarding if you manage your earnings beneath federal threshold limits.
Staying under the early earnings limit lets you collect your full paycheck alongside your monthly Social Security benefit.
Furthermore, part-time work provides valuable mental stimulation, creative purpose, and daily social connections that enrich retirement life.
For resources on retirement living, travel, and finance, visit AARP. Official information on Social Security is available at SSA.gov. For travel advisories, consult the U.S. Department of State.
Disclaimer: This article provides lifestyle suggestions for informational purposes. Financial, legal, or travel decisions should be made in consultation with qualified professionals.