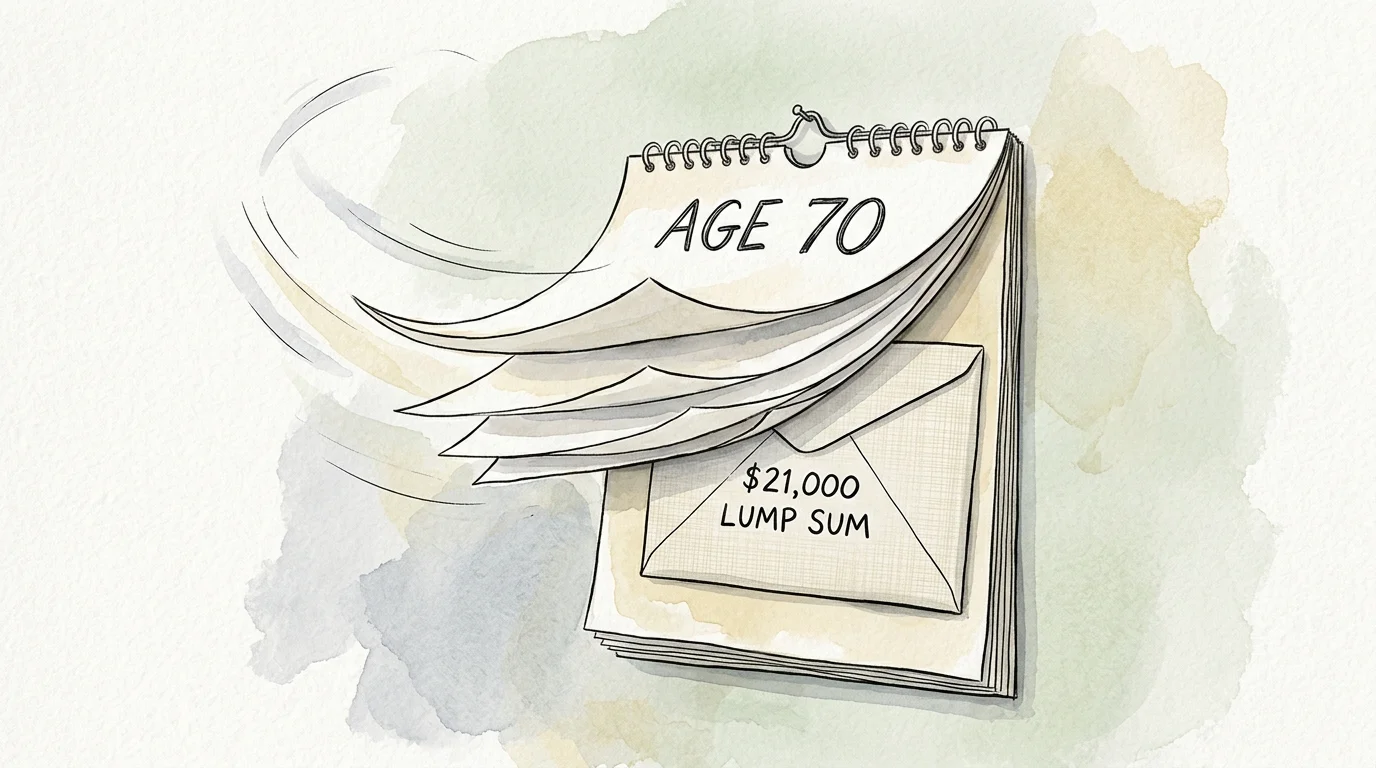
Tip #2: Claim Up to Six Months of Retroactive Benefits
Life moves fast, and sometimes your 70th birthday passes before you submit your retirement paperwork. Fortunately, the Social Security Administration offers a unique policy known as the six-month retroactive benefit rule. If you apply for your retirement benefits after reaching your Full Retirement Age, Social Security allows you to request up to six months of backdated cash benefits delivered in a single lump sum.
Understanding the math behind this rule helps you evaluate whether backdating aligns with your overall goals. If you apply at age 70 and a half, requesting six months of retroactive benefits backdates your official filing date to your 70th birthday. Because delayed retirement credits stop accruing at age 70 anyway, claiming this six-month lump sum provides immediate cash in hand without lowering your ongoing maximum age-70 monthly benefit rate. If your monthly benefit is $3,500, a six-month backdated payout puts $21,000 in your bank account right away.
Conversely, exercising this retroactive option before turning 70 requires careful thought. If you apply at age 69 and a half and request six months of retroactive benefits, Social Security backdates your claim to age 69. This action forfeits six months of delayed retirement credits—permanently reducing your lifetime monthly benefit check by 4%. Preserving your highest possible monthly check usually takes priority over short-term cash, but if you are already past 70, taking advantage of backdated payments offers a risk-free strategy to expand your liquid savings.
Very good and quite valuable information. THANK YOU for the article!