You can boost your retirement budget immediately by tapping into the hidden financial advantages of credit union membership. These member-owned cooperatives provide lower fees, better loan terms, and higher savings yields than commercial banks.
Whether you plan to travel across the country or preserve your nest egg, these member perks protect your everyday cash flow. Exploring your options will reveal practical financial benefits designed to enrich your golden years.
Here are ten outstanding credit union perks that can help you save money, simplify your estate management, and enjoy financial peace of mind.
Tip #1: Higher Savings Yields and Lower Borrowing Rates
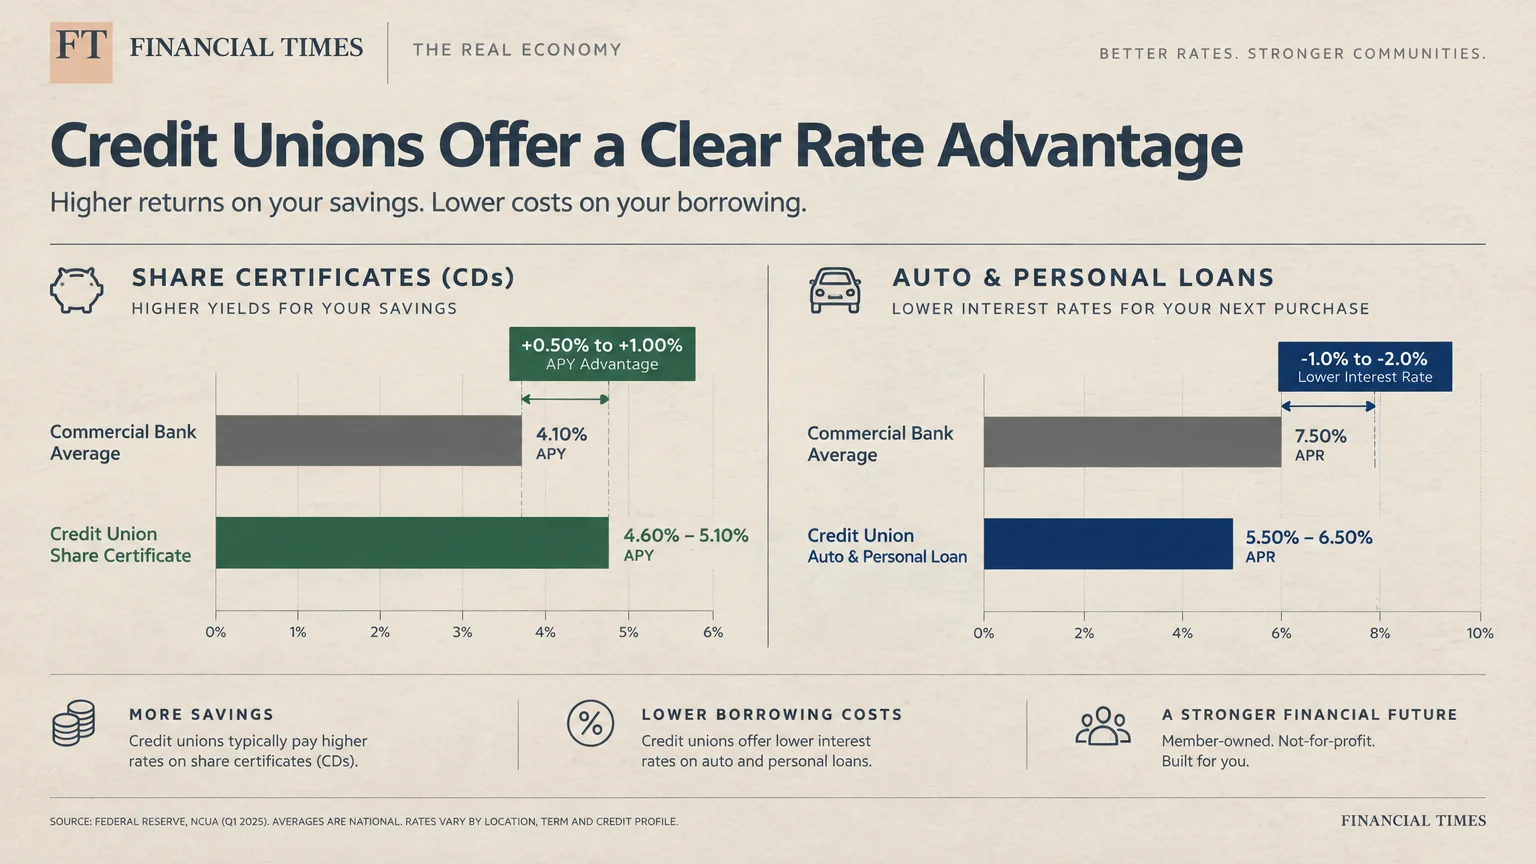
Switching your cash reserves to a credit union can instantly improve your monthly interest earnings. Credit unions consistently deliver higher annual percentage yields on certificates of deposit and savings accounts compared to national bank averages.
Data from the National Credit Union Administration reveals that credit union share certificates frequently yield 0.50% to 1.00% more than standard bank certificates. That difference adds real dollars to your monthly retirement cash flow.
You also benefit when borrowing money for a new vehicle, home renovation, or recreational travel. Credit union auto loans and personal lines of credit typically feature rates that are one to two percentage points lower than commercial bank loans.
Many retirees use share certificates to build predictable monthly income ladders. Staggering your certificate maturity dates allows you to capture rising interest rates while keeping access to your principal.
Because credit unions operate as not-for-profit cooperatives, they return surplus earnings directly to depositors. You keep more of your hard-earned wealth where it belongs—in your personal wallet.
Evaluating your credit union savings options helps you grow your nest egg safely; every extra dollar earned strengthens your retirement independence.
Tip #2: Nationwide Branch and ATM Convenience
You never have to sacrifice convenience when choosing a credit union over a mega-bank. Many retirees worry about traveling or spending winters down south without access to local financial offices.
Fortunately, the CO-OP Shared Branch network connects more than 5,600 physical credit union branches across all fifty states. You can walk into any participating credit union and complete teller transactions exactly as you would at home.
This cooperative network also grants you surcharge-free access to nearly 30,000 ATMs nationwide. You will easily find cash machines at popular grocery stores, retail pharmacies, and local convenience outlets.
You can withdraw travel cash, make mortgage payments, or deposit pension checks without incurring pesky out-of-network fees. This flexibility gives snowbirds and active travelers absolute freedom on the open road.
You can locate nearby partner locations in seconds using the free CO-OP mobile app or website directory. Navigating your daily banking needs while exploring scenic destinations has never been simpler.
When comparing a credit union vs bank setup, this cooperative network often rivals or exceeds the footprint of the largest commercial lenders.
Tip #3: The Statutory 18 Percent Interest Rate Cap
High credit card interest rates can quickly derail a carefully planned retirement budget. Fortunately, federal credit union members enjoy a statutory interest rate ceiling that protects them from predatory borrowing costs.
Under the Federal Credit Union Act, the National Credit Union Administration caps federal credit union loan and credit card interest rates at 18% APR. Regulators recently extended this protective cap through September 10, 2027.
Meanwhile, commercial bank credit cards regularly charge interest rates exceeding 21% to 25% APR on revolving balances. That sharp contrast saves cardholders hundreds of dollars during unexpected financial emergencies.
Even if you pay your monthly balance in full, this statutory protection brings tremendous reassurance. You can finance urgent medical bills or major home repairs without worrying about runaway compound interest rates.
Federal credit unions also avoid punitive default rate spikes if you accidentally miss an isolated payment due date. They prioritize fair treatment over penalty fees, keeping your credit rating and peace of mind secure.
This protective shield allows you to focus on enjoying your retirement activities rather than stressing over predatory bank charges.
Tip #4: Dedicated 50+ Senior Club Account Perks
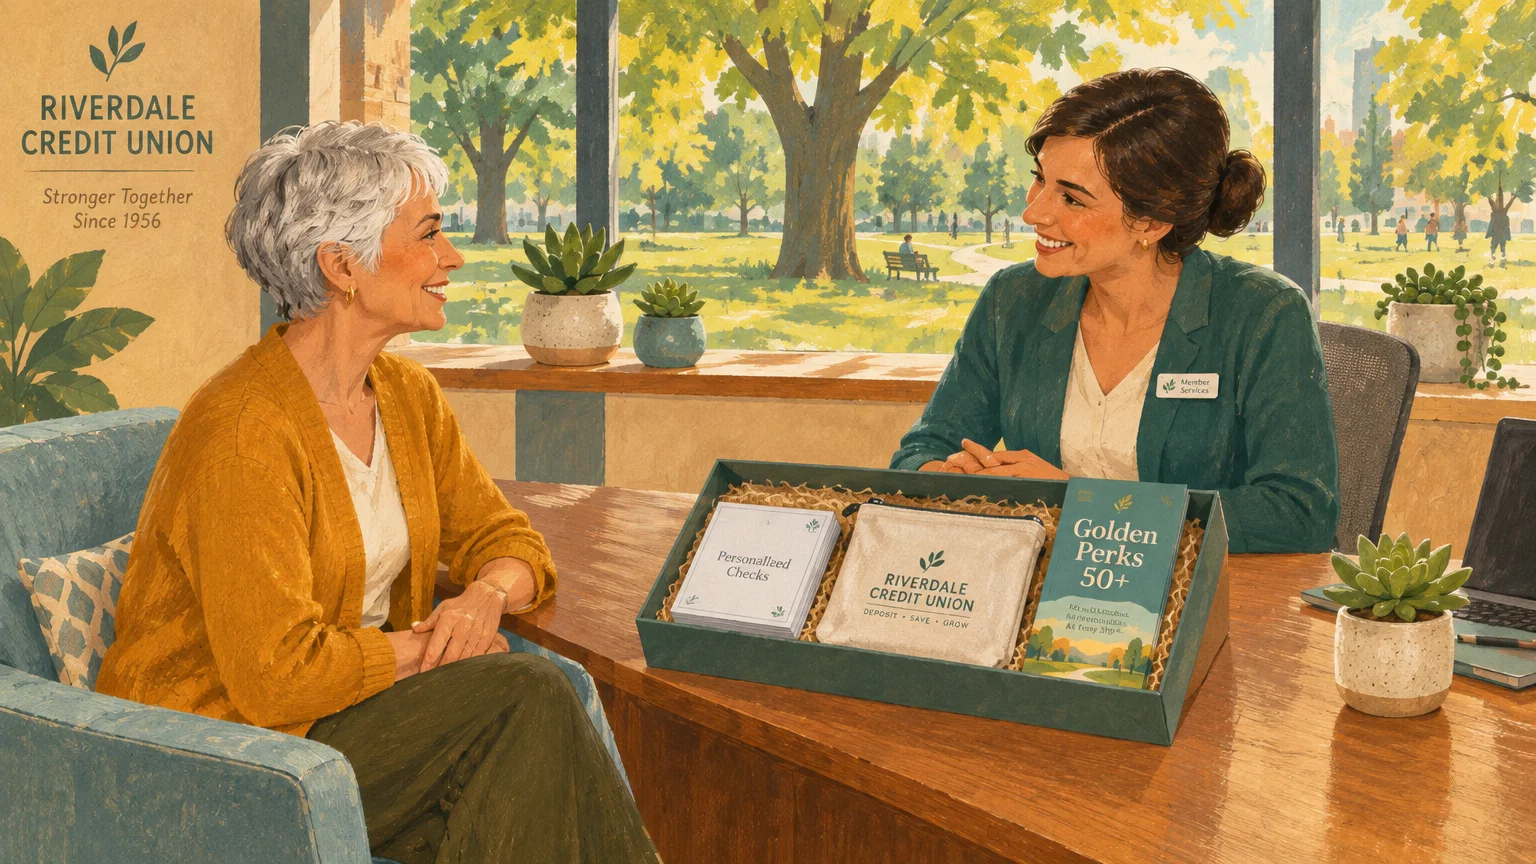
Many credit unions celebrate your life stage by offering specialized club checking accounts for adults aged fifty and older. These programs bundle premium everyday services at absolutely no extra charge.
If you prefer writing physical checks for your household bills, you can receive free printed check orders every year. Traditional banks often charge upwards of twenty-five dollars for a single box of paper checks.
These dedicated accounts frequently waive routine fees on cashier’s checks, official money orders, and incoming wire transfers. You can move funds or buy a vehicle without losing cash to minor processing fees.
Furthermore, you avoid annoying monthly maintenance fees and paper statement charges that drain conventional bank balances. Enjoying free account maintenance ensures your fixed retirement income remains fully intact each month.
Ask your local branch representative about their senior or mature member perks; a quick conversation could eliminate your regular banking costs permanently.
Taking advantage of these dedicated club accounts ensures your banking relationship remains affordable, comfortable, and tailored to your lifestyle.
Tip #5: Complimentary Medallion Signature Guarantees and Notary Services
Managing your retirement accounts and estate plans often requires specialized legal document authentication. A Medallion Signature Guarantee is mandatory when you transfer ownership of physical securities, stocks, or investment bonds.
Many commercial banks have quietly discontinued Medallion stamps or now charge steep fees ranging from ten to one hundred dollars per document. They also impose strict account tenure requirements before assisting you.
In contrast, most credit unions provide complimentary Medallion Signature Guarantees and notary services to their long-standing members. You simply schedule a quick visit with an authorized branch officer to complete your paperwork.
Whether you are rebalancing an investment portfolio or updating your family living trust, this free service saves valuable time and frustration. Having local, trusted staff review your legal forms brings genuine relief during complex transitions.
This perk proves especially helpful for surviving spouses who must re-title assets or distribute inheritances after a partner passes away. Compassionate branch staff make those difficult administrative tasks far more manageable.
This simple courtesy illustrates the customer-first philosophy behind credit union benefits; you receive essential financial support without constant nickeling and diming.
Tip #6: Meaningful Year-End Patronage Dividends and Rebates
When a traditional bank earns excess profits, it distributes those windfalls to external Wall Street stockholders. Credit unions operate under an entirely different philosophy centered on cooperative member ownership.
Because credit unions are member-owned non-profits, strong annual operating revenue returns straight to you. Many institutions distribute surplus earnings in December as year-end patronage dividends or bonus interest rebates.
If you keep substantial savings on deposit, you might receive a cash dividend credited directly to your primary share account. If you paid interest on a loan, you may receive an interest rebate back.
These surprise year-end payouts can provide a welcome financial boost right before the holiday season. You might use this extra cash to spoil your grandchildren, book a weekend getaway, or bolster your emergency fund.
Over several decades of retirement, these annual distributions can compound into thousands of dollars in bonus income. It feels great to see your financial institution share its good fortune directly with you.
Experiencing this direct return of capital confirms that your credit union membership truly represents an active partnership in your financial success.
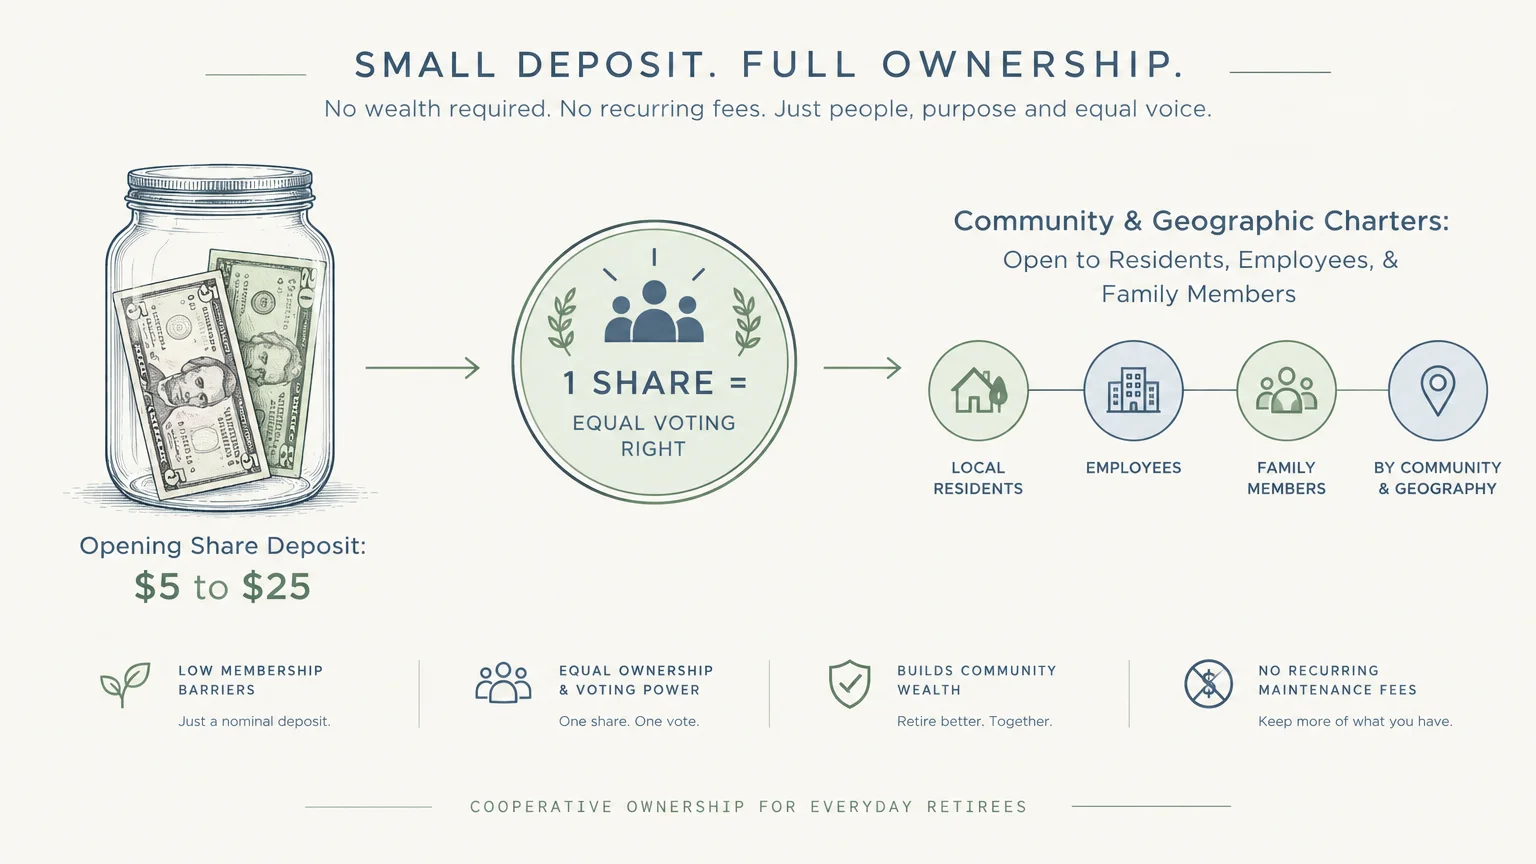
Tip #7: Low Opening Share Requirements and Accessible Membership
Opening an account at a premier commercial bank often requires keeping thousands of dollars locked in non-interest-bearing accounts. Credit unions eliminate these intimidating barriers with democratic, low-cost account requirements.
You establish lifetime credit union membership simply by purchasing a single ownership share, often known as the par value. This required deposit standardly ranges between five and twenty-five dollars.
That modest deposit stays safely tucked inside your primary savings account and establishes your equal voting rights. Every single member possesses an equal vote for the board of directors, regardless of total wealth.
Gaining membership is easier than ever before; modern credit unions welcome people through community residency, associations, or family connections. You rarely need complex credentials to join a top-tier local cooperative.
Once you join, you can usually sponsor your children and grandchildren so they can enjoy the same benefits. Passing this financial head start to younger generations creates lasting family stability.
With such low financial hurdles, you can easily secure membership and immediately begin utilizing valuable credit union perks.
Tip #8: Exclusive Discounts on Estate Planning and Tax Preparation
Your membership card also unlocks a treasure trove of national merchant discounts tailored specifically for household budgeting. Many credit unions participate in cooperative discount platforms like Love My Credit Union Rewards.
These partnerships offer substantial discounts on digital estate planning platforms such as Trust & Will. You can save up to 30% while creating legally binding wills, healthcare directives, and trusts.
You can also trim your annual tax preparation expenses with up to 20% off TurboTax federal products. If you prefer assisted tax filings, partnerships with H&R Block offer up to twenty-five dollars off in-office services.
Additionally, members can access discounted life, health, and property coverage through TruStage insurance programs. Many credit unions even provide complimentary basic accidental death coverage just for remaining an active member.
These bundled savings make protecting your estate and managing your annual taxes far more affordable. Taking advantage of these vendor partnerships puts hundreds of dollars back into your pocket every single year.
Exploring your member portal periodically ensures you never miss a new retail promotion or community discount.
Tip #9: Full Federal Deposit Insurance Backing
Protecting your hard-earned nest egg is the number one financial priority as you approach retirement. Some consumers mistakenly believe that credit unions are less secure than commercial banking giants.
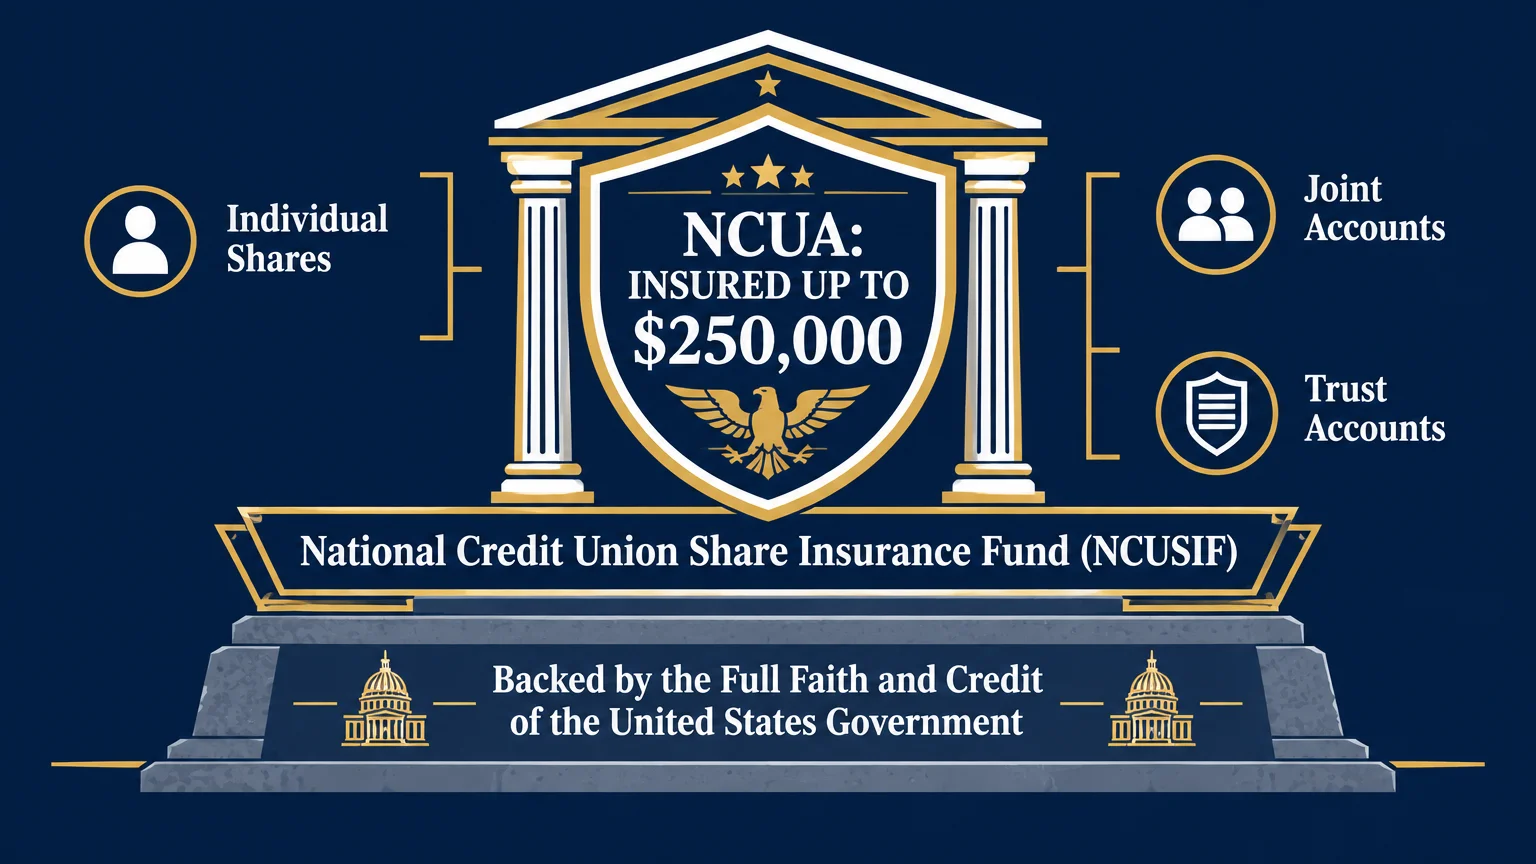
In reality, federal credit union deposits receive the exact same statutory protection and full-faith-and-credit backing as commercial banks. The National Credit Union Share Insurance Fund (NCUSIF) protects your money up to at least $250,000.
This protection applies per depositor, per institution, and across distinct ownership categories. You can insure much more than $250,000 by structuring individual, joint, trust, and retirement accounts thoughtfully.
For example, a married couple can readily protect up to $1,000,000 across their joint and individual accounts at a single institution. That statutory safety net provides total security for your liquid retirement assets.
Not a single member has ever lost a penny of insured savings within an NCUA-insured credit union. You can sleep peacefully knowing your money enjoys absolute government-backed safety.
This rock-solid safety net allows you to pursue higher yields without exposing your retirement nest egg to market risks.
Tip #10: Member-Centric Financial Wellness and Retirement Guidance
Big commercial banks frequently prioritize rapid sales quotas and high transaction fees over genuine customer care. Credit unions take the opposite path by focusing entirely on member financial wellness and personal support.
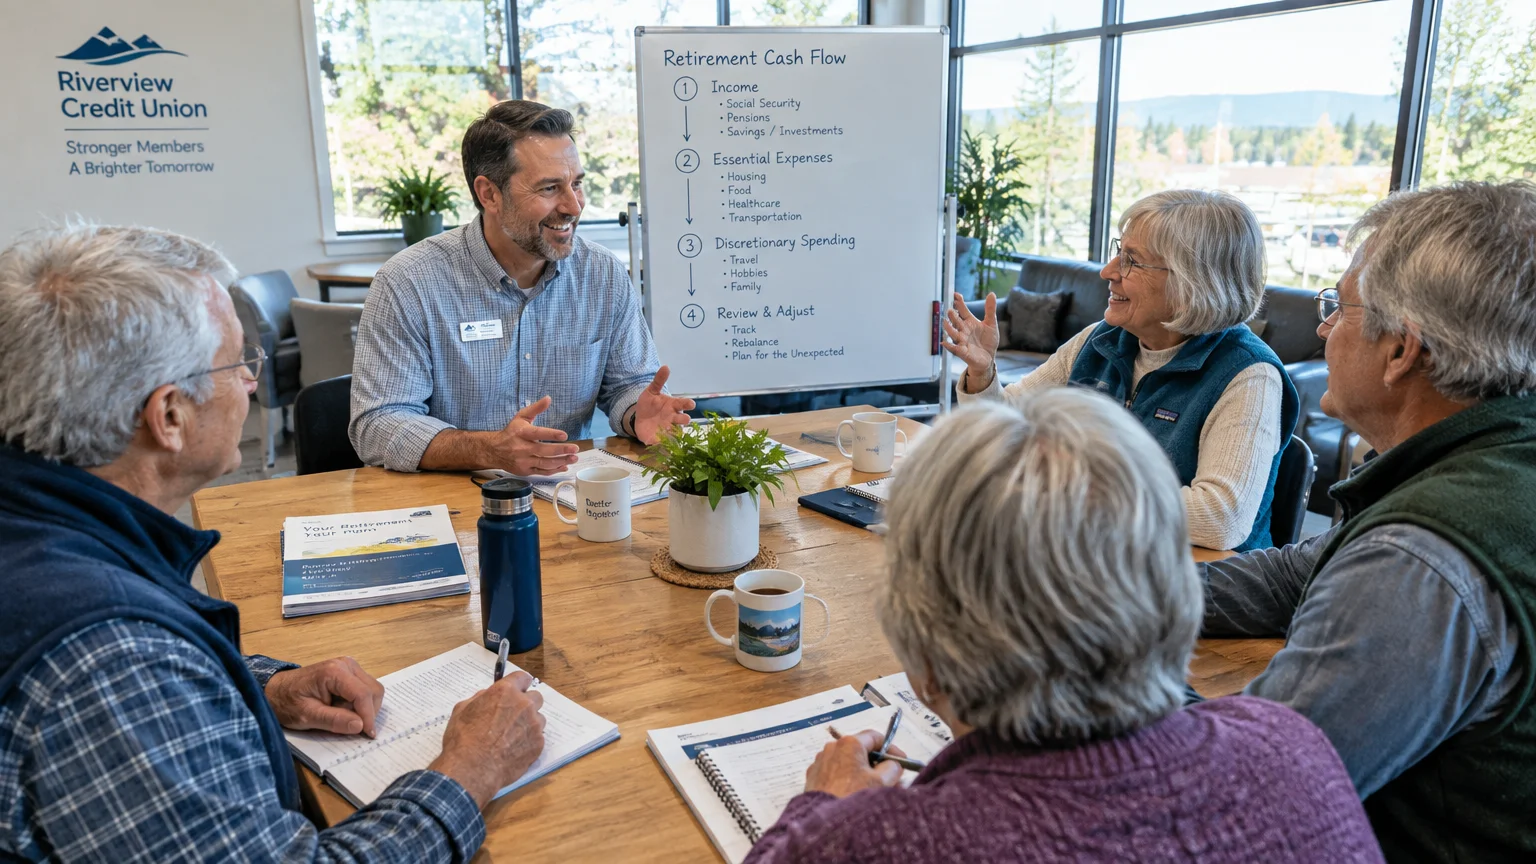
When you walk into a credit union branch, staff members take the time to understand your individual goals. They offer free financial counseling sessions, retirement planning seminars, and personalized debt management guidance.
Because loan officers are not motivated by aggressive commission structures, they recommend products that truly serve your best interests. They will guide you toward affordable loans and high-yield share certificates without high-pressure sales pitches.
Credit union staff are also trained to watch for suspicious account activity and protect seniors from predatory financial scams. Having watchful, local professionals looking out for your welfare provides an invaluable layer of security.
Many branches also partner with trusted local wealth advisors to assist you with required minimum distributions and estate planning. This supportive environment creates a true sense of community and long-term financial security.
Experiencing warm, respectful customer service turns routine banking into an uplifting, stress-free part of your retirement lifestyle.
The Takeaway: Living a More Blissful Retirement
Your retirement years should be filled with joyful adventures, peaceful mornings, and complete financial security. Aligning your finances with a community credit union provides practical tools to help you thrive.
From higher savings yields to waived administrative fees, these institutions treat you as an essential owner rather than an account number. You preserve more of your hard-earned wealth while enjoying compassionate personal service.
Take a few moments today to research the credit unions serving your community or professional background. Opening a primary share account could be one of the smartest and most rewarding financial moves you make this year.
Embrace the peace of mind that comes from knowing your banking partner truly has your back. You deserve a blissful retirement supported by institutions that honor your lifetime of hard work.
Frequently Asked Questions
How difficult is it for someone over 50 to qualify for credit union membership?
Joining a credit union is remarkably straightforward for modern retirees. While older rules restricted membership to specific employers, today most institutions accept anyone who lives, works, or worships in their geographic area.
Many organizations also offer membership through affiliated non-profit associations for a tiny one-time fee. A quick visit to a local branch or website will reveal several easy pathways to join.
Can I use out-of-state credit union branches when I travel during retirement?
Yes, you can access your money effortlessly thanks to the nationwide CO-OP Shared Branch network. Over 5,600 participating credit unions allow guest members to make deposits, withdraw funds, and cash checks in person.
You simply present your home credit union account number and a valid government photo identification to the teller. You will feel right at home no matter how far your retirement travels take you.
Are credit union deposits as safe as deposits held in large commercial banks?
Yes, your deposits enjoy the exact same degree of federal protection as traditional bank accounts. The National Credit Union Administration backs credit union deposits up to $250,000 per ownership category.
This coverage is backed by the full faith and credit of the United States government. Your retirement savings remain completely safe from loss at all times.
What is the difference between a bank certificate of deposit and a credit union share certificate?
Both accounts function almost identically by locking in a guaranteed interest rate for a specific term. However, because credit unions call their deposit accounts shares, their term deposit products are legally named share certificates.
Credit union share certificates typically pay higher annual yields because the cooperative returns excess revenue to members. They represent an exceptional, low-risk tool for generating predictable retirement income.
For a wide range of resources for older adults, visit AARP and the National Council on Aging (NCOA). Health information is available from the National Institute on Aging.
Disclaimer: This article is for informational and inspirational purposes only; it is not a substitute for professional medical, financial, or psychological advice. Please consult with a qualified expert for guidance tailored to your individual needs.